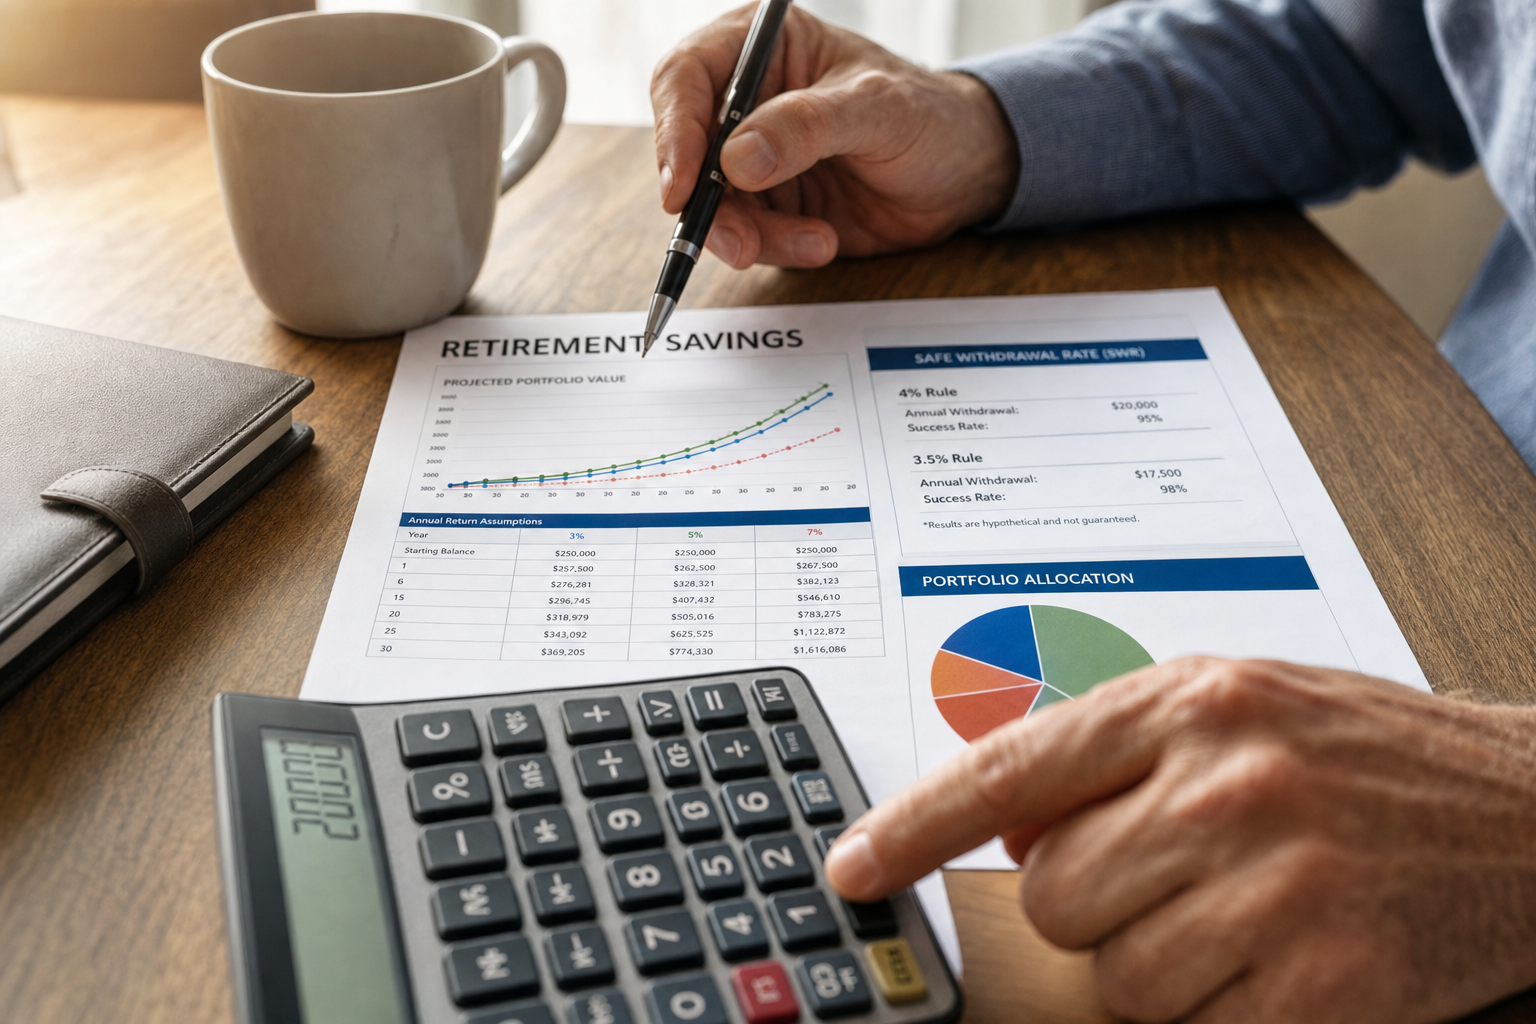
If you're approaching retirement, one of the biggest questions on your mind is probably some version of: how much can I actually spend each year without running out of money? That question has a name in financial planning circles. It's called your safe withdrawal rate, and understanding it (and its limits) can make the difference between a retirement plan that holds up and one that doesn't.
A safe withdrawal rate is the percentage of your retirement savings you take out in your first year of retirement, typically adjusting that dollar amount for inflation in the years that follow, with a reasonably high probability your money lasts as long as you need it to. It's a starting point for planning, not a guarantee. And the "right" number depends on more factors than most rules of thumb account for.
Key takeaways
- A safe withdrawal rate is a planning guideline, not an official government rule or regulatory standard.
- The traditional "4% rule" came from research in the 1990s; more recent analysis suggests a somewhat lower starting point may be appropriate for many retirees today.
- Your actual safe withdrawal rate depends on your retirement length, portfolio mix, spending flexibility, and other income sources like Social Security or a pension.
- Flexible spending strategies (adjusting withdrawals based on market performance) may support higher starting rates than a fixed, inflation-adjusted approach.
- Sequence-of-returns risk (poor market performance early in retirement) matters more than most people realize, and it's a key reason a static rule can fall short.
Where the 4% rule came from
The concept of a safe withdrawal rate traces back to research by financial planner William Bengen in the early 1990s, later reinforced by what's commonly known as the Trinity Study. Bengen looked at historical market returns and asked a simple question: if a retiree withdrew a fixed percentage of their portfolio in year one, then adjusted that dollar amount for inflation every year after, what withdrawal rate would have allowed the portfolio to last through the worst historical retirement periods? His research pointed to roughly 4% as a starting point that held up across most 30-year retirement periods in the data he studied.
That 4% figure became one of the most widely repeated numbers in retirement planning. It's simple, it's memorable, and it gave people a rule of thumb where none existed before. But it was always meant to be a starting point grounded in historical U.S. market data, not a promise about the future.
Why the rule of thumb has shifted
More recent research has revisited that 4% figure using updated market assumptions, valuations, and interest rate environments. Morningstar's 2026 retirement research puts a baseline starting withdrawal rate closer to 3.9% for a 30-year retirement with a balanced portfolio and a fixed, inflation-adjusted spending approach, aiming for a high probability (around 90%) that the portfolio still has funds remaining at the end.
That's not a dramatic change from 4%, but it illustrates an important point: the "safe" number isn't fixed in stone. It moves based on the assumptions used, including expected future returns, inflation, and how long the money needs to last. Anyone telling you a single percentage is permanently "correct" is oversimplifying.
What actually determines your number
Rather than fixating on a single percentage, it helps to understand the variables that push your personal safe withdrawal rate up or down.
Retirement length
A 35-year-old retiring early needs their money to last much longer than someone retiring at 68. Generally, a longer time horizon calls for a lower starting withdrawal rate, since the portfolio has more years of potential market downturns to weather.
Portfolio allocation
The mix of stocks and bonds in your portfolio affects both growth potential and volatility. Morningstar's 3.9% baseline assumes a balanced allocation, not an all-stock or all-bond approach, so your own allocation should factor into your personal number.
Sequence-of-returns risk
This is one of the most misunderstood pieces of retirement math. It's not just the average return over your retirement that matters, it's the order those returns come in. A market downturn in the first few years of retirement, while you're also withdrawing money, can do outsized damage to a portfolio compared to the same downturn happening later. This is why the first five to ten years of retirement often deserve extra attention and planning.
Spending flexibility
A fixed, inflation-adjusted withdrawal is the simplest approach to model, but it isn't the only option. Retirees willing to spend a bit less during down markets and a bit more when markets are strong may be able to sustain a higher starting withdrawal rate than a rigid, one-size-fits-all approach would allow.
Other guaranteed income
Social Security, pensions, and annuity income all reduce how much your investment portfolio needs to cover on its own. The more guaranteed income you have, the less pressure sits on your withdrawal rate.
Taxes
Withdrawals from tax-deferred accounts like traditional IRAs and 401(k)s are taxed as ordinary income, while withdrawals from Roth accounts generally are not. The order in which you draw from different account types can meaningfully affect how much you actually get to keep and spend.
Fixed rule versus flexible strategy
A fixed withdrawal approach is straightforward: pick a percentage, apply it to your starting balance, and adjust that dollar figure for inflation every year after, regardless of what the market does. It's easy to understand and easy to implement.
A dynamic or flexible strategy adjusts your withdrawals based on how your portfolio is actually performing. In strong years, you might take a bit more. In weaker years, you scale back. This approach can help extend how long a portfolio lasts and, in many cases, may support a higher starting withdrawal rate than a strictly fixed approach, though it asks more of retirees in terms of adjusting their spending along the way.
Common mistakes to avoid
- Withdrawing a flat dollar amount regardless of market performance. This ignores how your portfolio is actually doing and can accelerate depletion during a downturn.
- Ignoring sequence-of-returns risk in the early years. A rough market in year two or three of retirement can matter far more than the same rough market in year twenty.
- Treating your withdrawal rate as a "set it and forget it" number. Life changes, markets change, and your plan should be revisited periodically rather than left on autopilot for decades.
- Assuming a single percentage applies to everyone. Your retirement length, allocation, other income, and flexibility all shape what's realistic for you specifically.
When to talk with us
A safe withdrawal rate is a useful starting concept, but it's just that: a starting point. Every household's situation is different, shaped by how long retirement needs to last, how the portfolio is invested, what other income sources exist, and how much flexibility there is to adjust spending along the way. Building a personalized, ongoing withdrawal strategy, rather than leaning on a generic rule of thumb, is where real planning value comes in. If you're an Edmond or Oklahoma City area retiree or pre-retiree trying to figure out what number actually makes sense for your situation, it may help to schedule a call with us to talk through your specific numbers.
Frequently asked questions
Is the 4% rule still accurate in 2026? More recent research, including Morningstar's 2026 analysis, suggests a slightly more conservative starting point, around 3.9% for a 30-year retirement with a fixed, inflation-adjusted spending approach. It's a modest shift, not a dramatic one, but it shows the number isn't permanently fixed.
Is a safe withdrawal rate an official government guideline? No. It's a planning concept developed through financial research, not a rule set by the IRS, SSA, or SEC. Treat it as a helpful framework, not a regulatory requirement.
Does the safe withdrawal rate apply the same way to everyone? No. It varies based on your retirement length, portfolio allocation, spending flexibility, and other income sources like Social Security or a pension.
What is sequence-of-returns risk? It's the risk that poor market performance early in retirement, combined with ongoing withdrawals, can do more lasting damage to a portfolio than the same poor performance occurring later in retirement.
Can I withdraw more than the baseline rate? Possibly, if you're willing to adjust your spending based on market performance rather than committing to a fixed, inflation-adjusted amount every year. Flexible strategies may support higher starting withdrawals.
Does a longer retirement mean a lower withdrawal rate? Generally, yes. A longer time horizon means more years of potential market volatility for the portfolio to weather, which typically calls for a more conservative starting rate.
How does my portfolio allocation affect my withdrawal rate? Baseline research figures like the 3.9% cited by Morningstar assume a balanced mix of stocks and bonds. A more conservative or more aggressive allocation could shift what's sustainable for your specific portfolio.
Should I revisit my withdrawal rate every year? Periodic review is generally a good idea. Markets change, spending needs change, and a plan that made sense five years ago may need adjusting.
Do Social Security and pensions affect my safe withdrawal rate? Yes. Guaranteed income sources reduce how much your investment portfolio needs to cover on its own, which can change how much flexibility you have.
Is this the same as an official investment recommendation for my situation? No. This article is educational. Historical research and past returns don't guarantee future results, and building an actual withdrawal strategy for your household involves individualized planning that takes your full financial picture into account. That's what we're here to help with — schedule a call with us to work out your own customized plan.
Sources
This article is for informational and educational purposes only and does not constitute investment advice or a guarantee of future results. Historical research and past market returns do not guarantee future performance. Please consult a qualified financial advisor regarding your specific circumstances before making withdrawal or investment decisions.